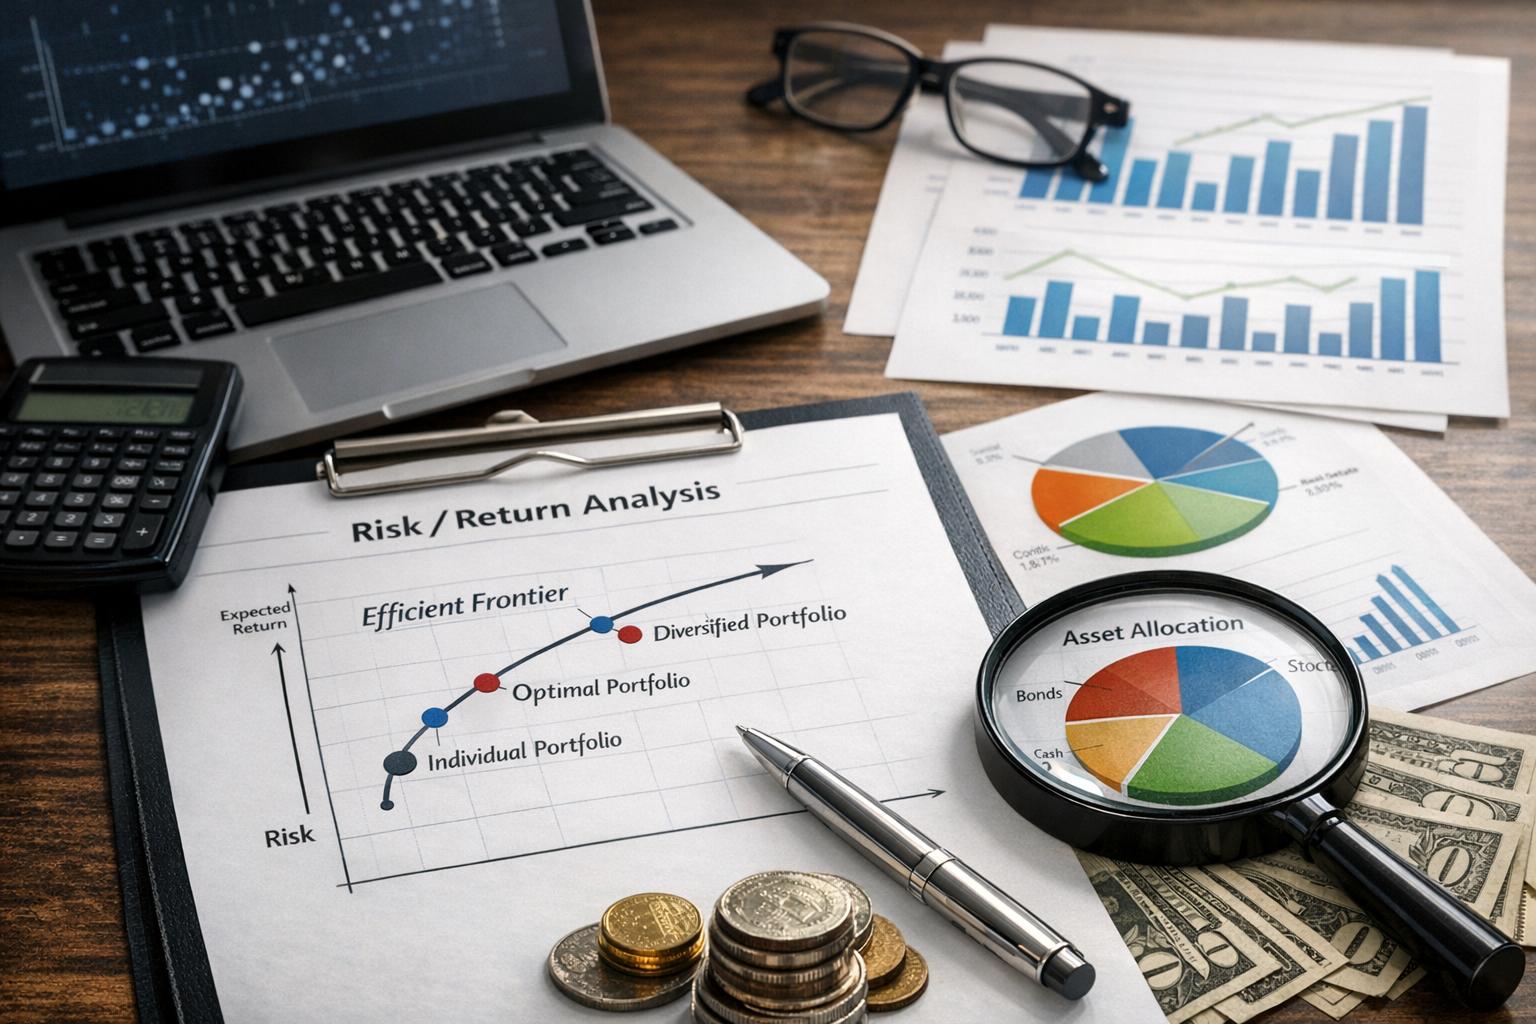
Portfolio theory examines how investors can combine assets to manage risk while pursuing an acceptable return. Rather than judging each investment on its own, the theory considers how shares, bonds, cash, property, and other holdings behave as a group. The central principle is fairly simple: portfolio risk may fall when assets do not rise and fall at the same time or by the same amount.
Efficient diversification does not mean collecting as many investments as possible. It means choosing a combination that offers the highest estimated return for a stated level of risk, or the lowest estimated risk for a stated return. A portfolio can hold hundreds of securities and remain poorly diversified if most depend on the same industries, currencies, interest-rate conditions, or sources of economic growth.
This distinction matters for private investors, pension funds, wealth managers, and traders who maintain longer-term holdings alongside active positions. The number of lines in a brokerage account says little by itself. What matters is the source of each holding’s risk, its weight, and its relationship with the rest of the portfolio.
The foundations of Modern Portfolio Theory
Modern Portfolio Theory, commonly abbreviated to MPT, was developed by economist Harry Markowitz and formally presented in his 1952 paper, Portfolio Selection. Markowitz argued that investors should assess an investment according to its contribution to total portfolio risk and return, rather than focusing only on the investment’s individual record.
Earlier investment analysis often concentrated on identifying attractive securities one at a time. An analyst might compare earnings growth, dividend yield, balance-sheet strength, or valuation ratios across several companies. Markowitz added a separate question: what happens to the whole portfolio when one of those securities is added?
This approach altered how professional investors thought about risk. A volatile security could improve a portfolio if its returns had a weak relationship with existing holdings. A relatively stable security could add little diversification if it reacted to economic events in much the same manner as assets already held.
Consider an investor who owns shares in several large banks. Adding another bank may spread exposure across management teams and loan books, but the portfolio remains dependent on credit conditions, financial regulation, funding costs, and the health of the economy. Adding government bonds may introduce a different return driver, although the result will depend on bond maturity, inflation, and prevailing interest rates.
MPT uses a mathematical framework, but its broader lesson does not require advanced mathematics. Investors should ask how a holding interacts with the portfolio, not only whether the holding looks attractive in isolation.
Expected return and portfolio weights
Expected return is an estimate of the return an asset may produce over a chosen period. Analysts may base the estimate on historical performance, dividend income, bond yields, valuation levels, economic forecasts, or a combination of methods. No estimate guarantees the result that will occur.
The expected return of a portfolio is the weighted average of the expected returns assigned to its holdings. The formula can be written as:
Expected portfolio return = Σ (asset weight × expected asset return)
Suppose 60% of a portfolio is invested in an equity fund expected to return 8% per year, with 40% in a bond fund expected to return 4%. The estimated portfolio return is:
(0.60 × 8%) + (0.40 × 4%) = 6.4%
The arithmetic is easy. Producing dependable return estimates is not. A small change in an assumption can materially alter a model’s preferred allocation. If the estimated equity return falls from 8% to 6%, the expected portfolio return drops to 5.2%, assuming all other inputs remain unchanged.
Portfolio weights also change as market prices move. If equities rise faster than bonds, equities gradually occupy a larger share of the account. The portfolio may then carry more volatility than the original allocation allowed. This is one reason investors review and rebalance holdings periodically.
Nominal and real returns
Expected returns may be stated in nominal or real terms. A nominal return does not deduct inflation. A real return measures the change in purchasing power after inflation.
If a portfolio earns 6% while consumer prices rise by 3%, the approximate real return is 3%. The exact calculation is:
Real return = [(1 + nominal return) ÷ (1 + inflation rate)] − 1
Using the same figures gives a real return of roughly 2.91%. The distinction matters for goals such as retirement spending, where purchasing power often matters more than the nominal account balance.
How portfolio risk is measured
Risk can refer to several different concerns. It may mean price volatility, permanent capital loss, failure to meet future spending needs, weak liquidity, inflation damage, or exposure to a concentrated issuer. Portfolio theory commonly uses variance and standard deviation because both can be calculated from return data.
Variance measures the average squared distance of returns from their mean. Standard deviation is the square root of variance and is easier to interpret because it uses the same units as returns. A higher standard deviation indicates that returns have historically moved across a wider range.
Suppose Fund A has produced an average annual return of 7% with a standard deviation of 8%, while Fund B has produced the same average return with a standard deviation of 15%. Under a conventional mean-variance analysis, Fund A has delivered the same return with less volatility. That does not prove Fund A will remain preferable. The result may reflect the period examined, the valuation starting point, or risks that have not yet appeared in historical prices.
Standard deviation also treats gains above the average as risk. Many investors welcome sharp gains and worry mainly about losses. Other measures can provide a fuller assessment, but no single number captures every form of investment risk.
Portfolio variance
Portfolio variance depends on asset weights, individual variances, and the relationships between asset returns. For a portfolio containing two assets, the formula is:
Portfolio variance = (w₁² × σ₁²) + (w₂² × σ₂²) + (2 × w₁ × w₂ × σ₁ × σ₂ × ρ₁₂)
In the formula, w represents each asset’s weight, σ represents standard deviation, and ρ represents correlation. The final term explains much of the diversification benefit. If correlation is below +1, combined volatility may be lower than a simple weighted average of the two assets’ volatilities.
Correlation and covariance
Correlation measures the strength and direction of the linear relationship between two sets of returns. It ranges from -1 to +1.
| Correlation value | General interpretation | Potential diversification effect |
|---|---|---|
| +1.0 | Assets move together in the same proportion | No volatility reduction from correlation |
| Between 0 and +1.0 | Assets tend to move in the same direction | Some reduction may occur |
| 0 | No consistent linear relationship | May provide a useful reduction |
| Between 0 and -1.0 | Assets tend to move in opposite directions | Stronger reduction may occur |
| -1.0 | Assets move in exactly opposite directions | A suitable weight could remove measured volatility |
Perfect positive and negative correlations are rare in traded markets. Most assets fall somewhere between the two extremes, and their relationships vary over time.
Covariance carries related meaning but is expressed in units linked to the underlying return data. A positive covariance indicates that returns tend to move in the same direction. A negative covariance indicates that one tends to rise when the other falls. Correlation standardises covariance, making comparisons between pairs of assets easier.
An investor may calculate a low historical correlation between domestic shares and long-term government bonds. That relationship may support diversification, but it is not a permanent law. If inflation rises quickly, both assets can fall together: shares may decline as expected profits are discounted at higher rates, while bond prices drop as yields rise.
Why correlations change during market stress
Correlations often rise during periods of market stress. Investors may sell several asset types at once to raise cash, meet margin calls, reduce leverage, or comply with risk controls. Securities that appeared only weakly related during calmer periods can then fall together.
Currency movements can also alter results. A foreign investment may rise in its home market but lose value after conversion into the investor’s domestic currency. Hedging the currency can reduce that exposure, though hedging introduces costs and may remove gains when exchange rates move favourably.
Correlation estimates should therefore cover more than one market phase. Reviewing rolling periods, recessionary intervals, inflationary periods, and sharp sell-offs can provide a better view than relying on one full-period average.
Systematic and unsystematic risk
Portfolio theory separates risk into two broad categories: systematic risk and unsystematic risk.
Systematic risk affects broad markets or large parts of the economy. Changes in interest rates, inflation, economic output, taxation, war, and investor risk appetite may influence thousands of securities at once. Ordinary diversification cannot remove this risk because most investments have some exposure to broad financial conditions.
Unsystematic risk, also called company-level or idiosyncratic risk, relates to an individual issuer or a narrow group. Examples include accounting fraud, a failed product, the loss of a major customer, a factory accident, or poor capital allocation by management. Holding securities from unrelated issuers can reduce the portfolio damage caused by any one event.
The early additions to a concentrated portfolio often produce the largest reduction in unsystematic risk. Moving from one company share to ten companies across several industries can materially change the risk profile. Moving from 300 broad-market holdings to 310 similar holdings is less likely to make a noticeable difference.
No fixed number of holdings guarantees adequate diversification. Ten large technology companies do not provide the same spread of economic exposure as ten companies drawn from unrelated industries and regions. Position weights matter as well. A portfolio with 50 securities may remain concentrated if one company accounts for half its value.
The efficient frontier
The efficient frontier represents portfolios offering the highest estimated return at each level of measured risk, or the lowest measured risk for each estimated return. Portfolios below the frontier are inefficient because another available combination offers a better estimated trade-off.
Analysts build the frontier by entering expected returns, standard deviations, and correlations for the assets being considered. An optimisation model then tests combinations of portfolio weights. The results are commonly plotted on a graph, with expected return on the vertical axis and standard deviation on the horizontal axis.
The frontier normally curves upward. Portfolios near its lower-left area have lower estimated risk and return. Portfolios farther to the right have higher estimated risk and return. The curve appears because mixing imperfectly correlated assets can produce risk levels that would not be available from either asset alone.
The portfolio with the lowest estimated variance is called the global minimum-variance portfolio. It sits at the far-left point of the feasible set. It may appeal to an investor focused on volatility control, but it does not automatically fit income needs, tax circumstances, liquidity requirements, or long-term growth targets.
Efficient does not mean suitable
A mathematically efficient portfolio may still be a poor fit for a real investor. The model might recommend a large allocation to long-term bonds even though the investor expects inflation to remain high. It might assign a large weight to an illiquid fund that restricts withdrawals. It may also propose frequent trades that create taxes and dealing costs.
Suitability depends on more than the location of a point on a graph. The investor’s time horizon, income stability, withdrawal plans, debt, emergency reserves, tax position, and reaction to losses all affect the allocation decision.
Risk tolerance and risk capacity should not be confused. Risk tolerance describes an investor’s willingness to accept fluctuations. Risk capacity describes the investor’s financial ability to bear losses. A person may feel comfortable with aggressive investments but have low capacity because the money will fund a house purchase next year.
The risk-free asset and capital allocation line
Portfolio theory often introduces a risk-free asset: an investment with a known return and no uncertainty about repayment over the selected period. Short-term government bills issued in the investor’s domestic currency often serve as a practical proxy.
The phrase risk-free is theoretical. Government bills may carry very low default risk, but the investor still faces inflation risk, reinvestment risk, taxation, and the chance that purchasing power will decline.
Combining a risk-free asset with a risky portfolio produces a line of possible risk-and-return combinations known as the capital allocation line. Holding part of the account in the risk-free asset reduces exposure to the risky portfolio. Borrowing to invest more than 100% in the risky portfolio increases exposure, though borrowing also introduces financing costs and greater loss potential.
The point where the best capital allocation line touches the efficient frontier is known as the tangency portfolio. Under the model’s assumptions, it has the highest Sharpe ratio among the risky portfolios available for analysis.
The Sharpe ratio
The Sharpe ratio estimates excess return per unit of volatility:
Sharpe ratio = (portfolio return − risk-free rate) ÷ portfolio standard deviation
Suppose a portfolio returned 9%, the risk-free rate was 3%, and portfolio volatility was 12%. Its Sharpe ratio would be 0.50. A second portfolio returning 8% with volatility of 8% would have a Sharpe ratio of 0.625, using the same risk-free rate. The second portfolio produced a lower raw return but a higher return relative to measured volatility.
Sharpe ratios require careful interpretation. Results depend on the time interval, return frequency, chosen risk-free rate, treatment of fees, and whether the data contain unusual market events. A strategy with infrequent small gains and rare large losses may show an attractive ratio before the large loss occurs.
Asset allocation as the practical application
Asset allocation determines how much capital goes into broad categories such as equities, government bonds, corporate bonds, cash, property, commodities, and other investments. It turns portfolio theory from an academic model into a practical investment plan.
Each asset class has different return drivers. Equities depend heavily on corporate earnings, valuation, economic growth, and investor sentiment. Bonds depend on interest rates, inflation, maturity, and issuer credit quality. Property returns are influenced by rental income, financing costs, occupancy, local supply, and capitalisation rates. Commodity prices respond to production, inventories, demand, weather, and political events.
| Asset class | Main role often assigned | Common risks |
|---|---|---|
| Equities | Long-term capital growth and dividend income | Market falls, business failure, valuation contraction |
| Government bonds | Income and defensive exposure | Interest-rate changes, inflation, sovereign credit risk |
| Corporate bonds | Income above government bond yields | Default, spread widening, low trading liquidity |
| Cash instruments | Liquidity and capital stability in nominal terms | Inflation and reinvestment at lower rates |
| Property | Rental income and possible inflation sensitivity | Vacancy, financing costs, valuation falls, illiquidity |
| Commodities | Inflation sensitivity and return diversification | Sharp price changes, storage costs, futures-curve effects |
Labels can conceal material differences. A short-term government bond fund behaves differently from a long-duration bond fund. An office property fund carries different risks from a portfolio of warehouses or residential buildings. A broad commodity index differs from a concentrated position in crude oil.
Diversification within asset classes
Allocating money across broad asset groups is only part of the process. Investors also need to consider concentration within each group.
Equity diversification
An equity allocation can be spread across industries, countries, company sizes, and investment styles. A portfolio may hold growth and value shares, large and smaller companies, and businesses earning revenue from different regions.
Geographic labels require care. A company listed in one country may earn most of its revenue abroad. Owning domestic and international funds can therefore produce overlapping business exposure. Large multinational companies may appear in several indexes through different funds.
Sector concentration can arise without the investor intending it. Market-capitalisation-weighted indexes assign larger weights to companies whose share prices and market values have risen. If one industry leads the market for several years, a broad index can become increasingly dependent on that industry.
Bond diversification
Bond portfolios can vary by issuer, credit rating, maturity, currency, and coupon structure. Holding bonds from several companies can reduce issuer risk, but it may not protect against a broad rise in interest rates or a recession that weakens many borrowers at once.
Duration estimates a bond portfolio’s sensitivity to yield changes. A duration of seven years suggests that a one-percentage-point rise in yields may produce a price decline of roughly 7%, before allowing for convexity and income. Mixing short-, medium-, and long-term bonds can spread maturity exposure, though it does not eliminate rate risk.
Credit quality also affects how bonds behave. High-quality government bonds may rise during an equity sell-off if investors prefer safer assets and expect rate cuts. Lower-rated corporate bonds can fall alongside equities because default concerns increase. Calling both holdings “bonds” does not make their risk profiles alike.
False diversification and overlapping funds
Owning several funds can create an appearance of diversification without much change in economic exposure. A broad domestic index fund, a large-company fund, and a technology-heavy growth fund may hold many of the same businesses. The account shows three positions, but a small set of companies may drive much of the result.
Fund names offer only a starting point. Investors can examine the largest holdings, sector allocations, country weights, index methodology, market-cap distribution, bond duration, and credit ratings. This review often reveals duplication that is not obvious from the account summary.
Funds may also differ in legal structure, replication method, securities-lending policy, currency treatment, and distribution policy. Those features do not always alter diversification, but they can affect costs, taxes, tracking difference, and trading behaviour.
Overlap is not automatically harmful. An investor may intentionally combine a broad fund with a smaller allocation to a favoured sector. The concern arises when duplication is accidental and leaves the investor carrying more concentration than planned.
Strategic and tactical asset allocation
Strategic asset allocation sets long-term target weights based on financial goals and acceptable risk. An investor might choose 60% equities, 35% bonds, and 5% cash, then restore those weights periodically.
The strategic approach assumes that maintaining a consistent risk profile matters more than making frequent forecasts. It can reduce trading and remove some pressure to respond to every economic headline. It does not prevent losses; a strategic portfolio still reflects market movements.
Tactical asset allocation temporarily changes target weights in response to valuations, economic forecasts, or market conditions. A manager may lower equity exposure after a large rise or shorten bond duration when expecting higher interest rates.
Tactical moves require two correct decisions: when to depart from the long-term allocation and when to return. Being early can resemble being wrong for quite a while. Taxes, spreads, commissions, and missed market rebounds can reduce any benefit from the forecast.
Some investors use a core-and-satellite structure. Most capital remains in a broad strategic allocation, while a smaller portion supports tactical positions. This can contain the effect of a failed market view, provided the satellite allocation remains modest and follows written limits.
Rebalancing and portfolio maintenance
Rebalancing returns a portfolio to its intended weights after market movements cause drift. Suppose an account begins with 60% equities and 40% bonds. After a strong equity rally, the mix reaches 70% equities and 30% bonds. The investor can sell equities, buy bonds, or direct new contributions into bonds.
Rebalancing controls allocation drift and imposes a repeatable process. It may involve selling assets after relative strength and buying assets after relative weakness. That discipline can feel uncomfortable because recent winners often appear more attractive than recent laggards.
Rebalancing does not guarantee better returns. During a prolonged equity rally, regularly selling shares to buy bonds may reduce performance. Its main purpose is risk control, not return maximisation.
Calendar and threshold rebalancing
Calendar rebalancing takes place at fixed intervals, perhaps every six or twelve months. It is simple to administer but may trigger trades when weights remain close to target.
Threshold rebalancing occurs when an allocation moves beyond a set band. A 60% equity target with a five-percentage-point band would trigger review below 55% or above 65%. This method responds to portfolio movement but requires monitoring.
A combined policy may review the account on a schedule and trade only when an allocation breaches its band. This avoids constant activity while preventing large departures from the chosen risk profile.
Taxes and trading costs
Rebalancing in taxable accounts may create capital gains. Investors can sometimes reduce the tax bill by using dividends, interest, or new contributions to purchase underweight assets. Trades inside pension or other tax-advantaged accounts may also help restore the household allocation without selling appreciated assets in a taxable account.
Bid-ask spreads and commissions matter more for small accounts, thinly traded securities, and frequent rebalancing. A theoretically improved allocation may not justify the cost of moving a very small amount of money.
Human capital and assets outside the portfolio
Financial accounts form only part of an investor’s economic position. Employment income, business ownership, property, pensions, debt, and future spending commitments can change the appropriate portfolio mix.
An employee who receives salary, bonuses, and company shares from one employer has concentrated exposure to that employer. If the company struggles, income and investment wealth may fall at the same time. Reducing employer-share exposure can improve financial resilience, even if the shares have performed well.
Human capital also varies by occupation. A tenured public-sector employee may have relatively stable income that resembles a bond-like stream. A commission-based property broker may have income closely linked to economic and property cycles. The broker may prefer less property exposure in an investment account than someone whose income is unrelated to that sector.
Home ownership creates another concentration. A house may represent a large share of net worth and ties wealth to one local market. The property also differs from a traded investment because it provides housing services and may carry emotional value, transaction costs, and mortgage debt.
Liquidity and time horizon
Liquidity describes how readily an asset can be sold at a price near its quoted or estimated value. Public shares and major government bonds often trade quickly under normal conditions. Private equity, direct property, and some credit funds may require months or years to exit.
An illiquid holding may report smooth returns because valuations occur infrequently. That smoothness should not be mistaken for low economic risk. A building valued every quarter will usually show less apparent volatility than a share priced every second, even if both are exposed to changing economic conditions.
Time horizon affects how much short-term fluctuation an investor can bear, but a long horizon does not make risk disappear. It provides more time for recovery and allows regular contributions to purchase assets at different prices. It does not guarantee that an asset bought at a high valuation will deliver an adequate return.
Money needed within a few years generally calls for more attention to liquidity and capital stability. Long-term capital can accept more market fluctuation if the investor has sufficient reserves and can remain invested during falls.
Inflation and diversification
Inflation reduces the purchasing power of money and can affect asset classes in different ways. Cash may preserve nominal value while losing real value. Fixed-rate bonds can suffer because their future payments buy fewer goods and because market yields may rise. Equities may pass higher costs to customers, but their response depends on pricing power, debt, valuation, and economic growth.
Inflation-linked bonds adjust principal or interest according to an inflation index. They can help protect real purchasing power when actual inflation exceeds market expectations. Their prices may still fall when real interest rates rise.
Property and commodities are sometimes used as inflation-sensitive assets. Their protection is inconsistent. Property income may adjust slowly through rent reviews, while financing costs can rise rapidly. Commodities may respond strongly to supply shocks but produce no ongoing income and can experience severe price swings.
Inflation diversification works best when the investor considers the source of inflation rather than treating all inflationary periods as alike. Demand-led inflation, supply shortages, currency weakness, and wage growth can affect assets in different ways.
Portfolio stress testing
Historical volatility and correlation provide useful data, but they should not be the only inputs in a risk review. Stress testing asks how a portfolio might respond to adverse events.
A test may estimate the effect of a sharp equity decline, a rapid rise in bond yields, a widening of corporate credit spreads, a currency move, or a fall in property values. Investors can also combine shocks, since difficult markets rarely respect neat categories.
Scenario analysis does not predict the next crisis. It identifies concentrations and funding problems before they become urgent. If a 25% equity fall would force an investor to sell assets needed for near-term spending, the allocation may carry too much market risk.
Stress tests should consider liquidity and leverage as well as price changes. A leveraged position can require extra collateral after a fall. An investment fund may restrict withdrawals. A security may have a quoted price but little trading volume at that price.
Shortfall risk, drawdown, and downside measures
Standard deviation is widely used, though investors often care more about falling short of a goal than about ordinary price movement. Several measures address that concern from different angles.
Maximum drawdown measures the largest fall from a prior peak to a subsequent trough during the period examined. It shows the severity of the worst historical decline but says nothing about a worse event that has not yet occurred.
Downside deviation measures returns below a chosen target, rather than treating upside and downside movement alike. The target may be zero, the risk-free rate, or a required return.
Value at risk, commonly called VaR, estimates a loss threshold for a stated probability and period. A one-day 95% VaR of £10,000 suggests that modelled losses should exceed £10,000 on about 5% of trading days. It does not state how large those worse losses may be.
Expected shortfall estimates the average loss in the tail beyond the VaR threshold. It gives more attention to severe outcomes, though it remains dependent on data and model assumptions.
No measure deserves sole authority. Reviewing several measures can expose risks that standard deviation alone misses.
Fees, taxes, and implementation
Portfolio models often present returns before the frictions faced by investors. Real accounts incur fund charges, advisory fees, commissions, spreads, custody charges, taxes, and foreign-exchange costs.
A one-percentage-point annual cost can have a large effect over several decades because the investor loses both the fee and the future growth that money might have earned. Cost control cannot prevent market losses, but it is one of the few portfolio variables an investor can influence directly.
Low-cost index funds and exchange-traded funds can provide broad exposure with relatively few transactions. Investors still need to inspect the tracked index, replication method, fund size, trading spread, tax treatment, and currency exposure.
Active funds may provide differentiated holdings or risk controls, but higher fees create a higher hurdle. Performance should be assessed after fees and, where relevant, after taxes. A fund that beats its benchmark before charges may still leave investors behind after all expenses.
Behavioural pressures on diversification
Portfolio plans often fail because of behaviour rather than mathematics. Investors may chase recent winners, abandon assets after weak periods, or hold excessive amounts of familiar companies. Familiarity can feel safer without reducing financial risk.
Performance chasing tends to increase concentration after prices have already risen. An investor may add technology shares after several strong years or sell bonds after rates have risen and prices have fallen. Such decisions can turn a balanced allocation into a collection of yesterday’s winners.
Loss aversion also affects rebalancing. Buying an underperforming asset can feel unreasonable, even when the position remains appropriate and has fallen below its target weight. A written process reduces the need to make each decision from scratch.
An investment policy statement can record return aims, acceptable loss levels, target weights, rebalancing bands, liquidity needs, permitted investments, and reasons that would justify a policy change. Market news alone is rarely a sound reason to rewrite the plan.
Limits of portfolio optimisation
Portfolio optimisation relies on estimates. Expected returns are especially difficult to forecast, and small input changes can produce very different recommended weights. This is sometimes called estimation error.
An optimiser may assign a very large allocation to an asset with a slightly higher estimated return or a slightly lower correlation. Such precision can be misleading. Weight constraints, conservative assumptions, and rounded allocations can produce portfolios that are easier to implement and less dependent on one forecast.
Historical return distributions also contain more extreme events than a normal distribution would suggest. Markets can gap, trading liquidity can disappear, and correlations can rise rapidly. Models based on normal returns may understate the frequency and severity of large losses.
Data periods present another problem. Using ten years of history may place heavy weight on one interest-rate cycle. Using fifty years introduces market structures, regulations, and inflation conditions that may no longer resemble the present. There is no perfect sample.
Optimisation should therefore serve as a decision aid rather than an instruction machine. Economic reasoning, implementation costs, investor circumstances, and stress tests should accompany the mathematical output.
Building an efficiently diversified portfolio
The process starts with the investor rather than with a fund list. Goals, withdrawal dates, income needs, emergency reserves, tax status, and capacity for loss determine which risks are acceptable.
The next step is to choose broad asset exposures with different return drivers. Each holding should have a defined role, such as long-term growth, income, liquidity, inflation protection, or defensive behaviour during equity weakness. If two holdings perform the same role and own many of the same securities, one may be redundant.
Position size deserves as much attention as security selection. A holding can add diversification at a moderate weight and create concentration at an excessive weight. The portfolio should also account for exposures created by employment, property, business ownership, and debt.
Implementation should favour clarity. A portfolio that requires constant interpretation is harder to maintain through difficult markets. More holdings mean more records, more chances for overlap, and more rebalancing decisions. Complexity needs to earn its place.
Regular review remains necessary, but constant trading usually is not. A review can examine allocation drift, issuer concentration, fund overlap, bond duration, credit quality, currency exposure, liquidity, costs, and changes in personal circumstances. Daily price movement rarely justifies a structural change.
What efficient diversification can and cannot do
Efficient diversification can reduce avoidable concentration, spread company-level risk, and improve the relationship between expected return and measured volatility. It can also make a portfolio less dependent on one forecast, one issuer, or one economic outcome.
It cannot prevent losses during broad market declines. It cannot make unreliable return estimates accurate, guarantee that past correlations will continue, or remove the effects of inflation, tax, and poor investor behaviour. Even a well-diversified portfolio can experience a severe drawdown.
The practical aim is not to own every available investment. It is to hold a manageable group of assets whose roles are clear, whose risks differ in useful ways, and whose combined behaviour fits the investor’s financial needs. That may sound less exciting than finding the next standout share, but portfolio management is often better when it is a little boring.
Portfolio theory provides a disciplined framework for making trade-offs. Higher expected returns generally require accepting greater uncertainty. Lower volatility often comes with lower expected growth or greater exposure to inflation. An efficient portfolio does not remove those trade-offs; it arranges them deliberately and keeps them aligned with the investor’s capacity to remain invested.